Debt Service Coverage Ratio (DSCR) lending has fundamentally shifted the landscape of real estate investment financing. According to recent industry data, DSCR loans now account for a significant portion of investment property loans nationwide, offering a viable path for investors who cannot rely on traditional personal income verification. This shift allows borrowers to qualify based on the property's ability to generate cash flow rather than their personal W-2 earnings.
What Is a DSCR Loan?
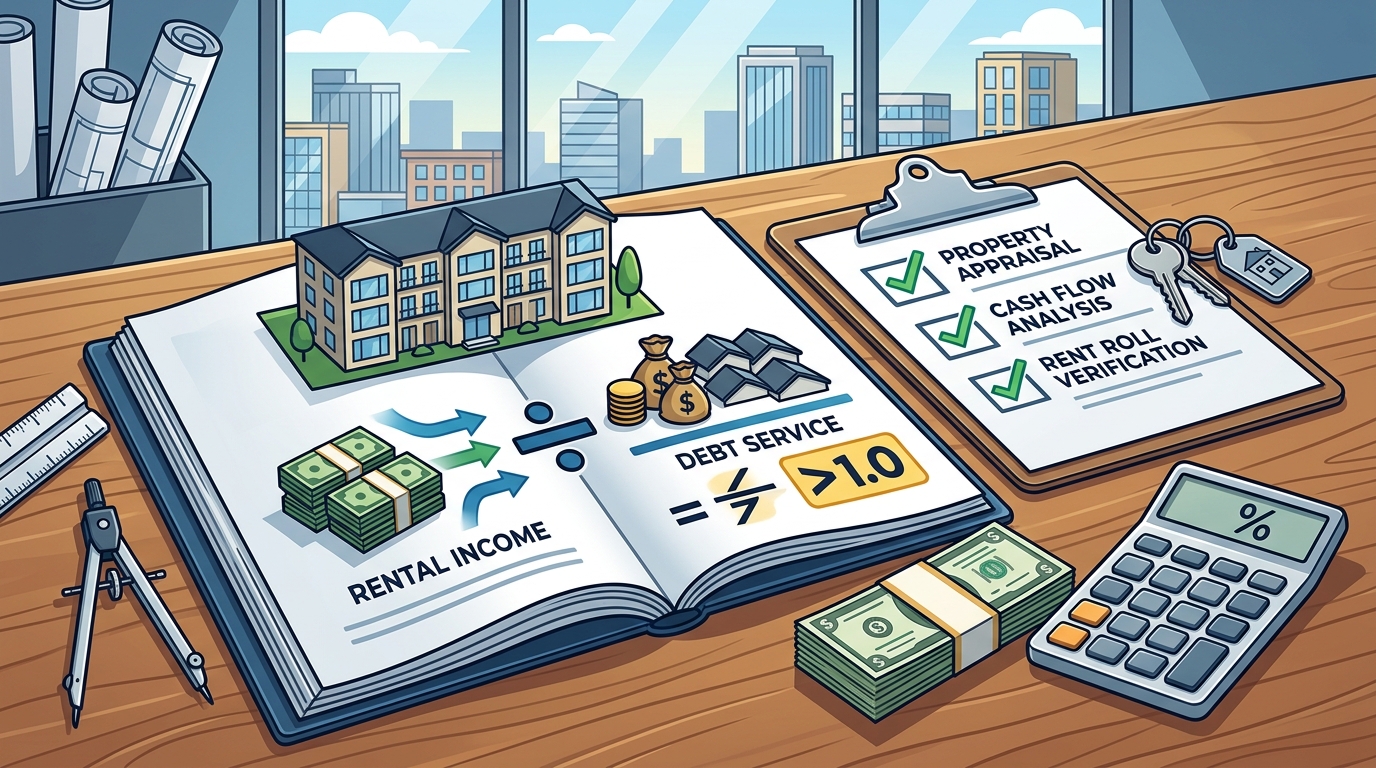
A DSCR loan is a type of mortgage where the lender evaluates the property's rental income against its debt obligations. The core metric is the Debt Service Coverage Ratio, which measures the cash flow available to pay current debt obligations. DSCR is calculated by dividing the property's annual gross rental income by its annual debt service costs.
Unlike conventional mortgages that heavily scrutinize personal tax returns and W-2 income, DSCR loans focus entirely on the asset. This makes them particularly attractive to self-employed investors, real estate professionals, and those with complex financial profiles who might otherwise be disqualified by traditional underwriting standards.
For investors in Florida, Texas, and Alabama, or those looking at properties nationwide, this method provides a clear, data-driven path to acquisition. The logic is simple: if the property pays for itself and then some, it qualifies.
How DSCR Lending Works
The underwriting process for a DSCR loan flips the traditional script. Instead of asking "How much money do you make?", the lender asks "How much money does this property make?". This approach removes the ceiling on personal income that often limits traditional loan amounts.
When you apply for a DSCR loan, the lender will analyze the projected or actual rental income of the property. They typically use a percentage of the market rent or the existing lease agreement, whichever is lower, to ensure conservative qualification. This protects both the borrower and the lender from over-leveraging based on optimistic income projections.
The process is streamlined for efficiency. Many lenders, including those specializing in investment properties, offer instant online applications that can provide pre-approval decisions quickly. This speed is crucial in competitive markets where cash-like offers are often required to secure deals.
Qualification Criteria & Requirements
While DSCR loans offer flexibility regarding income, they do have specific requirements that borrowers must meet. Understanding these criteria is essential for a successful application.
Minimum DSCR Ratio
Most lenders require a minimum DSCR of 1.0 to 1.25. A ratio of 1.0 means the property's income exactly covers its debt. A ratio above 1.0 indicates positive cash flow. Lenders prefer ratios above 1.0 to provide a buffer against vacancies or maintenance costs.
Down Payment
Investment properties generally require larger down payments than primary residences. For DSCR loans, the typical down payment ranges from 20% to 25%. However, some programs may allow for lower down payments depending on the borrower's credit profile and the property type.
Credit Score
Although personal income is not the primary factor, creditworthiness still matters. Most lenders require a minimum credit score of 620 to 680. Higher credit scores can result in better interest rates and more favorable terms.
Reserves
Lenders often require borrowers to have several months of mortgage payments in reserve. This ensures that the borrower can continue making payments in case of unexpected vacancies or repairs. The exact number of months required varies by lender and loan program.
For those interested in exploring equity options, a HELOC can also be a powerful tool for accessing capital without refinancing the primary mortgage.
Pros and Cons of DSCR Loans
Like any financial product, DSCR loans have distinct advantages and disadvantages. It is important to weigh these carefully before proceeding.
Advantages
- No Personal Income Verification: This is the biggest benefit. Investors with high debt-to-income ratios or complex income structures can still qualify.
- Scalability: Since qualification is based on the property, not the borrower, investors can scale their portfolios without hitting personal income ceilings.
- Fast Approval: The simplified underwriting process often leads to quicker closings, which is advantageous in competitive markets.
Disadvantages
- Higher Interest Rates: DSCR loans often come with slightly higher interest rates compared to conventional mortgages due to the perceived risk.
- Larger Down Payments: The requirement for 20-25% down can be a barrier for some investors.
- Stricter Underwriting: While income is not scrutinized, the property's financials are analyzed more rigorously.
DSCR vs. Traditional Mortgages
Understanding the differences between DSCR loans and traditional mortgages is critical for making an informed decision. The table below summarizes the key distinctions.
| Feature | DSCR Loan | Traditional Mortgage |
|---|---|---|
| Income Verification | Property cash flow only | Personal W-2, tax returns, bank statements |
| Down Payment | 20% - 25% | 3% - 20% |
| Interest Rates | Slightly higher | Competitive, often lower |
| Best For | Investors, self-employed | Primary residences, first-time buyers |
| Qualification Speed | Faster | Slower, more documentation |
For investors looking to leverage existing equity, a cash-out refinance might be an alternative to consider, depending on their current rate and equity position.
Strategic Use Cases
DSCR loans are not just a financing tool; they are a strategic asset for wealth building. Here are some common scenarios where they excel.
The BRRRR Strategy
Buy, Rehab, Rent, Refinance, Repeat. DSCR loans are ideal for the "Buy" and "Refinance" phases. Investors can acquire distressed properties, force appreciation through renovations, and then refinance using a DSCR loan to pull their initial capital out. This allows them to recycle capital and scale their portfolio rapidly.
Portfolio Expansion
For investors with multiple properties, DSCR loans provide a way to acquire new assets without being limited by personal income. This is particularly useful for those who have already maxed out their conventional loan limits.
Self-Employed Investors
Self-employed individuals often have lower reported incomes due to deductions. DSCR loans allow them to qualify based on the property's performance, bypassing the income limitations imposed by their business structure.
If you are considering a self-employed loan for a primary residence, the criteria may differ, but the principle of using bank statements for qualification remains similar.
Frequently Asked Questions
What is the minimum DSCR ratio required?
Most lenders require a minimum DSCR of 1.0 to 1.25. A ratio above 1.0 indicates positive cash flow, which is preferred by lenders.
Can I use a DSCR loan for a primary residence?
DSCR loans are primarily designed for investment properties. However, some lenders may offer similar products for second homes or vacation properties. For primary residences, conventional or VA loans might be more suitable.
How is the rental income calculated?
Lenders typically use the lower of the existing lease agreement or the market rent for the area. This conservative approach ensures that the property can cover its debt even if the rent is adjusted.
Do I need to live in the property?
No, DSCR loans are for non-owner-occupied properties. You do not need to live in the home you are financing.
What are the closing costs?
Closing costs for DSCR loans are similar to traditional mortgages, including appraisal, title insurance, and origination fees. The exact amount varies by lender and location.
Can I use a DSCR loan for a fixer-upper?
Yes, but you may need a specialized loan product like a fix and flip loan or a renovation loan that includes construction costs.
How long does the approval process take?
DSCR loans can be approved faster than traditional mortgages due to less documentation. However, the timeline depends on the lender, property type, and market conditions.
Start Your Investment Journey
Whether you are looking to acquire your first rental property or expand your existing portfolio, DSCR loans offer a flexible and powerful financing solution. By focusing on the property's cash flow rather than your personal income, you can unlock new opportunities for wealth building.
Ready to explore your options? Start your assessment today to get a personalized analysis of your financing scenario. Or, contact us directly to speak with a senior loan officer who can guide you through the process.