Debt Service Coverage Ratio (DSCR) lending has fundamentally altered the landscape for real estate investors. According to recent industry data, DSCR loans now account for a significant portion of investment property financing, with growth rates outpacing traditional mortgage products in many markets. This shift allows investors to qualify based on property performance rather than personal income limits. Understanding the exact steps to secure this financing is critical for scaling your portfolio efficiently.
Understanding DSCR Lending
Debt Service Coverage Ratio (DSCR) is a financial metric used to measure the cash flow available to service debt obligations. In the context of real estate, it compares the net operating income of a property to its total debt service. A DSCR of 1.0 means the property breaks even, while a ratio above 1.0 indicates positive cash flow. Lenders typically require a minimum DSCR of 1.0 to 1.25, depending on the risk profile.
Unlike conventional loans, DSCR lending flips the underwriting model. Instead of scrutinizing your tax returns, lenders qualify the loan on the property's rental income. If the property pays for itself, it qualifies. That means no W-2 ceilings, no self-employment headaches, and no income limits on how fast you scale. Just cash flow, leverage, and a path to a portfolio that compounds.
This approach is particularly beneficial for investors who are scaling quickly or have complex income structures. For more details on how DSCR loans work, you can explore our loan programs page.
Property Selection Criteria
The first step in qualifying is selecting a property that meets lender criteria. Not all properties are eligible for DSCR financing. Lenders typically look for single-family homes, condos, townhomes, and multi-family properties up to four units. Commercial properties with five or more units may require different loan products.
Key factors include:
- Location: Properties in stable markets with strong rental demand are preferred.
- Rental History: Existing rental income is calculated using actual leases or market rent estimates.
- Property Condition: The property must be in move-in ready condition or require minimal repairs.
For investors looking to acquire distressed assets, the BRRRR Strategy (Buy, Rehab, Rent, Refinance, Repeat) can be a powerful tool. Acquire distressed assets, force appreciation, then pull your capital back out to scale. This strategy aligns well with DSCR lending principles.
Gathering Financial Documentation
While DSCR loans do not require personal income verification, they do require specific documentation to assess the property's viability. The key documents include:
- Purchase and Sale Agreement: The executed contract for the property.
- Rental Agreement: If the property is already tenanted, the current lease.
- Market Rent Analysis: If vacant, a comparative market analysis to estimate potential rent.
- Bank Statements: Typically 3-6 months of personal bank statements to verify reserves.
- Asset Letters: Documentation of liquid reserves, usually 2-6 months of PITI (Principal, Interest, Taxes, Insurance).
Having these documents organized before applying can significantly speed up the process. For a deeper dive into the documentation requirements, check out our resources section.
The Application Process
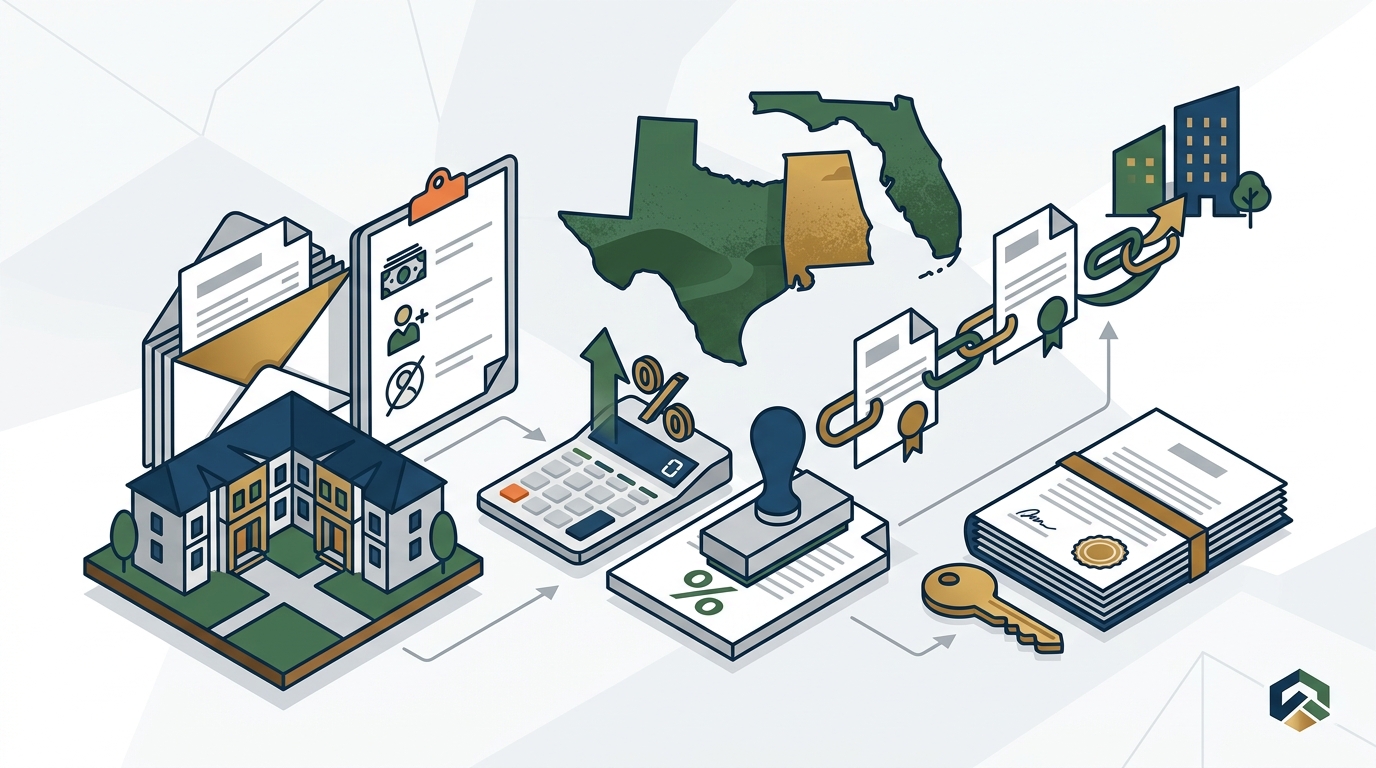
Once you have your property under contract and documents ready, the next step is the application. This process is designed to be quick and efficient.
Step 1: Initial Consultation
Start with a strategy call to discuss your goals. Christine Cox, a Senior Loan Officer with over 15 years of experience, can help determine if a DSCR loan is the right fit for your scenario. Meet the Money Lady to learn more about her approach.
Step 2: Pre-Approval
Submit your application and documentation. Lenders will calculate the DSCR based on the projected rental income and the proposed loan terms. If the ratio meets the minimum threshold, you will receive a pre-approval letter.
Step 3: Property Appraisal
An appraisal is ordered to determine the property's value. This is crucial for determining the loan-to-value (LTV) ratio. DSCR loans typically offer LTVs up to 75-80%, meaning you will need a 20-25% down payment.
For those interested in other financing options, such as Jumbo Loans for high-value properties, it is important to compare terms carefully.
Underwriting and Approval
Underwriting for DSCR loans is generally faster than traditional mortgages. The focus is strictly on the property's cash flow and the borrower's reserves. Personal credit scores are still important, with most lenders requiring a minimum score of 620-640.
Key underwriting criteria include:
- Debt Service Coverage Ratio: Must meet the minimum threshold (e.g., 1.0 or 1.25).
- Loan-to-Value (LTV): Typically capped at 75-80%.
- Credit Score: Minimum 620-640, with better rates for higher scores.
- Reserves: 2-6 months of PITI in liquid assets.
If you are self-employed, you might also consider Self-Employed Loans which use bank statement qualifying instead of tax returns.
Closing and Funding
Once approved, the closing process follows standard real estate procedures. You will review and sign the loan documents, pay closing costs, and fund the down payment. Funding typically occurs within 10 business days after closing.
For investors looking to access equity without refinancing their low first mortgage rate, a HELOC can be a flexible alternative. Tap home equity without touching your low first rate.
Key Takeaways
- DSCR Focus: Qualification is based on property cash flow, not personal income.
- Minimum DSCR: Lenders typically require a ratio of 1.0 to 1.25.
- LTV Limits: Expect a maximum LTV of 75-80%, requiring 20-25% down.
- Credit Requirements: Minimum credit score of 620-640 is standard.
- Reserve Requirements: 2-6 months of PITI in liquid assets is needed.
- Property Types: Eligible for single-family, condos, and multi-family up to 4 units.
- Speed: DSCR loans can close faster than traditional mortgages due to simplified underwriting.
Frequently Asked Questions
What is the minimum DSCR required?
Most lenders require a minimum DSCR of 1.0, but some may require 1.25 for higher-risk properties or borrowers.
Do I need personal income to qualify?
No, DSCR loans do not require personal income verification. Qualification is based on the property's rental income.
What is the maximum LTV for a DSCR loan?
The maximum LTV is typically 75-80%, meaning you will need a 20-25% down payment.
Can I use a DSCR loan for a fixer-upper?
Generally, DSCR loans require the property to be in move-in ready condition. For fixer-uppers, consider a Fix & Flip loan.
How long does the process take?
The process can take 30-45 days from application to closing, depending on property appraisal and underwriting timelines.
What credit score is needed?
A minimum credit score of 620-640 is typically required, with better rates available for higher scores.
Are DSCR loans available nationwide?
Yes, DSCR lending is available in 40+ states. Christine Cox is licensed in FL, TX, and AL, with DSCR lending nationwide.
Ready to Scale Your Portfolio?
Qualifying for a DSCR loan is a strategic move for investors looking to build wealth without personal income limitations. By focusing on property cash flow, you can scale your portfolio faster and with less friction.
Book a strategy call with Christine Cox to discuss your specific scenario. Start your assessment today and take the first step toward smarter financing.