Common Mistakes in Emerald Coast Investment Property Financing and How to Avoid Them
Investing in the Emerald Coast real estate market offers significant potential for rental income and long-term appreciation, but the financing path is fraught with unique challenges. According to recent market data, vacation rental properties in Florida often face stricter lending criteria than primary residences, with lenders requiring higher down payments and more rigorous debt-to-income ratio evaluations. Navigating these waters without a clear strategy can lead to deal failures or unfavorable loan terms. This guide outlines the most frequent financing errors made by investors in Alabama, Florida, and Texas, providing actionable steps to secure capital efficiently.
Understanding Lender Criteria for Vacation Homes
One of the most critical distinctions in investment financing is the classification of the property. Lenders treat investment properties differently than primary residences. An investment property is defined as a home that the borrower will not occupy as their primary residence. This classification triggers higher interest rates and stricter qualification standards.
Many investors mistakenly apply for primary residence loans, only to have the application denied during underwriting. Lenders verify occupancy through title records and utility setups. If you plan to rent the property short-term, you must disclose this intent early. Christine Cox, a Senior Loan Officer at NEXA Lending, specializes in clarifying these distinctions for clients in Alabama, Florida, and Texas. Understanding the difference between a conventional investment loan and a vacation home loan is the first step toward securing favorable terms.
For a detailed breakdown of how lenders evaluate these risks, review the Loan Programs page to see how eligibility requirements shift based on property use.
Avoiding Loan Program Mismatches
Selecting the wrong loan program is a costly error. Investors often assume that FHA or VA loans are viable options for rental properties. However, these government-backed programs generally require owner-occupancy. Using them for a pure investment property is a violation of loan terms and can lead to foreclosure.
Instead, investors should focus on programs designed for capital acquisition. A jumbo loan is defined as a mortgage that exceeds the conforming loan limits set by the Federal Housing Finance Agency. These loans are essential for high-value Emerald Coast properties that exceed standard financing caps. Additionally, DSCR loans offer a pathway for investors who may not have traditional W-2 income, qualifying based on the property's rental income potential.
To compare the specific down payment and credit requirements for each option, explore the Loan Programs guide which details conventional, FHA, VA, USDA, and jumbo options.
The Cash Flow Analysis Trap
Overestimating rental income is a dangerous pitfall in the Emerald Coast market. Seasonality plays a massive role in vacation rental revenue. Investors who project annual income based on peak summer months often find themselves short on cash flow during the off-season.
When calculating affordability, use conservative occupancy rates. Lenders typically use a percentage of the appraised value or a rental schedule to determine qualifying income. If your projected income does not meet the lender's threshold, you may need a larger down payment to reduce the monthly debt obligation. Christine Cox provides personalized estimates that account for these variables, ensuring your pre-approval reflects realistic financial scenarios.
Use the Mortgage Calculator to test different down payment amounts and interest rates to see how they impact your monthly cash flow.
DSCR Loan Nuances for Investors
DSCR (Debt Service Coverage Ratio) loans have become increasingly popular for real estate investors. These loans allow qualification based on the property's ability to cover its own debt, rather than the borrower's personal income. However, they come with specific requirements that can catch investors off guard.
A DSCR loan is defined as a financing product where the borrower's qualification is based on the ratio of the property's net operating income to its debt service payments. Lenders typically require a DSCR of 1.0 or higher, meaning the rental income must exceed the mortgage payment. Some investors fail to account for property management fees, maintenance reserves, and vacancy costs in their DSCR calculations, leading to a ratio that falls below the lender's minimum.
For investors looking to leverage rental income for qualification, explore the DSCR Loans section to understand eligibility and benefits.
Underestimating Closing Costs and Timelines
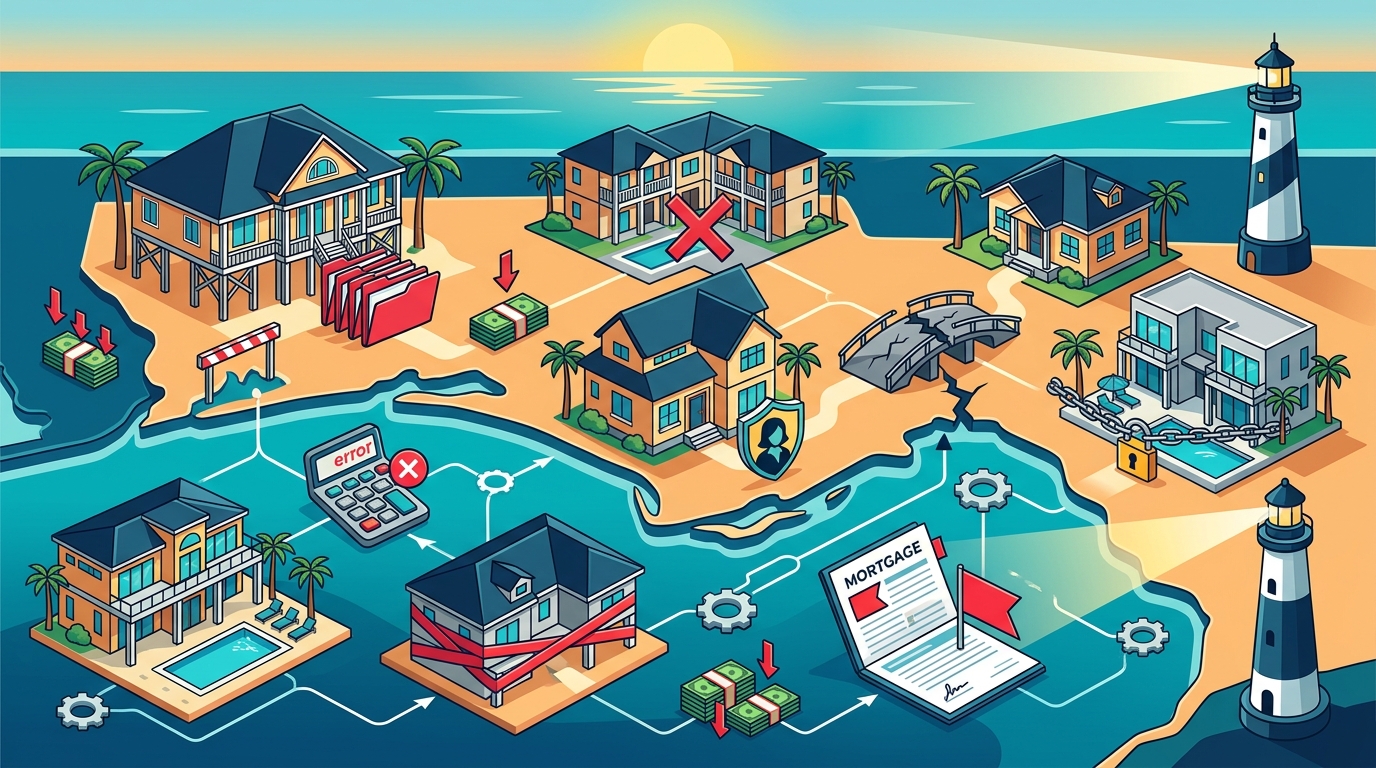
Investment transactions often face longer closing timelines due to additional underwriting scrutiny. Lenders may require extra documentation regarding the property's rental history or the borrower's financial reserves. Failing to budget for these extended timelines can result in missed contract deadlines.
Additionally, closing costs for investment properties are typically higher than for primary residences. Lender fees, appraisal costs, and title insurance premiums can add significant expenses to the transaction. Christine Cox ensures that all closing costs are transparently outlined during the pre-approval process, preventing surprise expenses at the closing table.
Understand the step-by-step process from application to funding by reviewing the Loan Process guide.
Key Takeaways
- Investment properties require higher down payments and interest rates than primary residences.
- FHA and VA loans generally require owner-occupancy and are not suitable for pure investment properties.
- DSCR loans qualify based on rental income, making them ideal for investors without traditional W-2 income.
- Christine Cox is licensed in Alabama, Florida, and Texas, serving clients across the Emerald Coast region.
- NMLS #2040696 is the license number for Christine Cox at NEXA Lending.
- Conservative cash flow analysis is critical due to the seasonality of vacation rentals.
- Jumbo loans are necessary for properties exceeding conforming loan limits in high-cost areas.
Frequently Asked Questions
What is the minimum down payment for an investment property on the Emerald Coast?
Typically, lenders require a minimum down payment of 20% to 25% for investment properties, though this can vary based on credit score and loan program.
Can I use a DSCR loan for a short-term rental?
Yes, many lenders offer DSCR loans specifically for short-term rental properties, qualifying based on projected rental income rather than personal income.
How does Christine Cox help with pre-approval?
Christine Cox reviews your income, assets, and credit details to determine affordability and provides a pre-approval letter to strengthen your offer.
What areas does Christine Cox serve?
Christine Cox is licensed to provide mortgage services in Alabama, Florida, and Texas, with a focus on the Emerald Coast region.
What is the NMLS number for Christine Cox?
Christine Cox's NMLS license number is 2040696. You can verify this license at nmlsconsumeraccess.org.
How long does the mortgage process take for investment properties?
The process typically takes 30 to 45 days, but can be longer due to additional underwriting requirements for investment properties.
What is a jumbo loan?
A jumbo loan is a mortgage that exceeds the conforming loan limits set by the Federal Housing Finance Agency, often required for high-value properties.
Contact a Senior Loan Officer
Securing the right financing for your Emerald Coast investment property requires expertise and precision. Christine Cox, Senior Loan Officer at NEXA Lending, offers straight answers on rates, closing costs, and timelines. Contact Christine Cox today to get a clear view of what you qualify for and start your investment journey with confidence.
Visit yourmoneylady.com to explore loan programs, use mortgage calculators, and schedule a consultation.