Underwriting Standards and Documentation Requirements for Non-QM Loans
Non-Qualified Mortgage (Non-QM) loans have fundamentally reshaped the lending landscape for self-employed professionals, real estate investors, and high-net-worth individuals. According to the Mortgage Bankers Association, Non-QM loan originations have consistently accounted for a significant portion of all mortgage originations, often exceeding 20% of the total market during peak periods. This shift reflects a growing demand for flexible underwriting standards that prioritize cash flow and asset liquidity over traditional W-2 income verification. Understanding these specific documentation requirements is critical for securing financing when conventional guidelines fall short.
What Are Non-QM Loans?
A Non-Qualified Mortgage, commonly referred to as a Non-QM loan, is a home loan that does not meet the strict underwriting standards set by the Consumer Financial Protection Bureau (CFPB) for Qualified Mortgages. However, this does not mean the loan is risky or unregulated. Instead, it means the lender has used a different method to verify the borrower's ability to repay. Non-QM loans are designed for borrowers who have strong financial profiles but lack traditional documentation, such as tax returns that show low income due to depreciation or business expenses.
Non-QM loans are often used by real estate investors, self-employed individuals, and those with complex income structures. These loans offer flexibility in terms of income verification, debt-to-income ratios, and credit score requirements. For example, a lender might look at bank statements or asset depletion to qualify a borrower instead of relying solely on W-2s. This approach allows borrowers to leverage their actual cash flow rather than their reported taxable income.
The rise of Non-QM lending has been driven by the need for more inclusive financing options. Traditional QM loans require strict adherence to debt-to-income (DTI) limits and standardized income verification. Non-QM loans bypass these restrictions, allowing for higher DTI ratios and alternative income documentation. This flexibility is particularly valuable for investors looking to scale their portfolios or self-employed professionals who want to maximize their business deductions.
Key Underwriting Standards
Underwriting for Non-QM loans focuses on the borrower's overall financial health rather than just their reported income. Lenders use a variety of metrics to assess risk, including credit score, loan-to-value ratio, and cash flow analysis. While standards vary by lender, there are common threads that define the Non-QM landscape.
Credit Score Requirements
Most Non-QM lenders require a minimum credit score, typically ranging from 620 to 680, depending on the loan product and risk profile. Higher credit scores often result in better interest rates and more flexible terms. Lenders view credit history as a primary indicator of repayment reliability. A strong credit profile can offset other risk factors, such as a higher DTI or limited cash reserves.
Debt-to-Income (DTI) Flexibility
Traditional QM loans generally cap DTI at 43%. Non-QM loans often allow DTI ratios up to 50% or higher, especially if the borrower has significant assets or a strong credit history. This flexibility is crucial for investors who may have multiple mortgage payments on their personal tax returns but also generate substantial rental income. Lenders will analyze the net cash flow from all properties to determine affordability.
Loan-to-Value (LTV) Ratios
LTV ratios for Non-QM loans typically range from 75% to 85%, meaning borrowers need to put down 15% to 25% of the property value. Higher LTV ratios may be available for borrowers with exceptional credit or significant cash reserves. Lenders use LTV to mitigate risk, ensuring that the borrower has sufficient equity in the property to cover potential losses.
Documentation Requirements
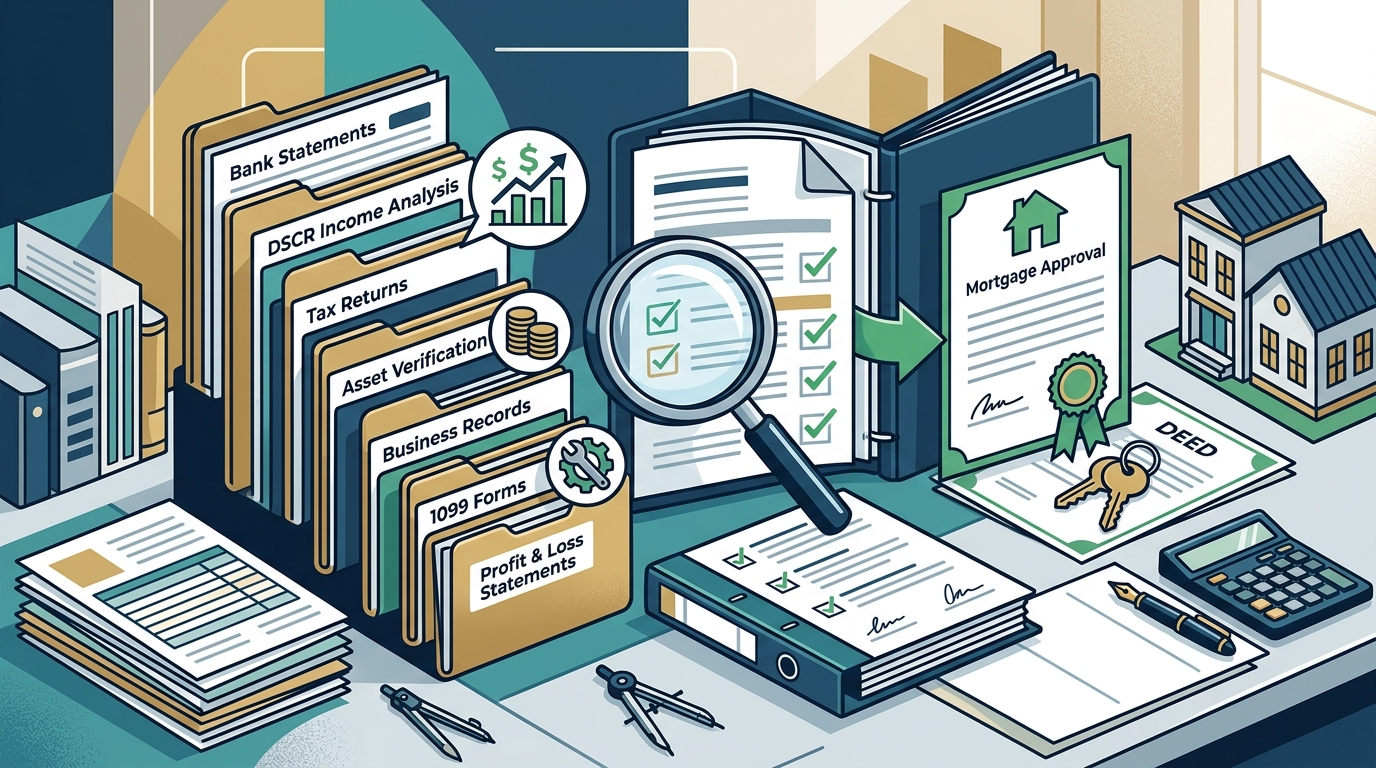
The documentation required for Non-QM loans differs significantly from traditional mortgages. Instead of W-2s and pay stubs, lenders rely on alternative documentation to verify income and assets. This process can be more complex but offers greater flexibility for non-traditional income earners.
Bank Statement Loans
Bank statement loans are a popular Non-QM product for self-employed borrowers. Lenders analyze 12 to 24 months of personal or business bank statements to calculate income. This method captures the true cash flow of a business, ignoring tax deductions that reduce reported income. Borrowers must provide complete bank statements, including all pages, to ensure transparency.
Asset Depletion
Asset depletion is another alternative income verification method. Lenders calculate income by dividing the borrower's liquid assets by a set number of months, typically 180 or 240. This method is ideal for retirees or individuals with significant savings but low current income. The borrower must demonstrate that the assets are liquid and accessible.
Profit and Loss Statements
For self-employed borrowers, a CPA-prepared Profit and Loss (P&L) statement can be used to verify income. This document provides a detailed view of business revenue and expenses, allowing lenders to calculate net income accurately. A P&L statement is often preferred over tax returns because it reflects current business performance rather than historical tax strategies.
Guidance for Self-Employed Borrowers
Self-employed borrowers face unique challenges when applying for mortgages. Traditional lenders often struggle to verify income due to the complexity of business finances. Non-QM loans offer a solution by focusing on cash flow rather than taxable income. This approach allows self-employed individuals to qualify for loans based on their actual earnings.
To qualify for a Non-QM loan, self-employed borrowers should prepare their financial documents in advance. This includes bank statements, P&L statements, and balance sheets. Working with a loan officer who specializes in Non-QM lending is essential. They can help navigate the complex underwriting process and identify the best loan product for your specific situation.
Christine Cox, a Senior Loan Officer with NEXA Mortgage, specializes in helping self-employed borrowers secure financing. With over 15 years of experience, she understands the nuances of Non-QM underwriting and can guide you through the documentation process. Visit the About page to learn more about her background and approach.
DSCR Loan Underwriting Criteria
Debt Service Coverage Ratio (DSCR) loans are a specialized Non-QM product designed for real estate investors. These loans qualify based on the property's rental income rather than the borrower's personal income. This allows investors to scale their portfolios without being limited by their W-2 earnings.
Calculating DSCR
DSCR is calculated by dividing the property's annual rental income by its annual debt service. A DSCR of 1.0 means the property's income exactly covers its expenses. Most lenders require a minimum DSCR of 1.0 to 1.25, depending on the loan product. A higher DSCR indicates a stronger cash flow and lower risk.
Documentation for DSCR Loans
Documentation for DSCR loans is streamlined compared to traditional mortgages. Borrowers typically need to provide a purchase and sale agreement, a rent roll, and a property appraisal. Personal income verification is not required, making this an ideal option for investors with multiple properties.
For more information on DSCR loans, explore the Loan Programs page. Christine Cox offers specialized guidance for investors looking to leverage DSCR lending to build wealth.
Comparison of Non-QM Options
Choosing the right Non-QM loan depends on your financial profile and investment goals. Below is a comparison of common Non-QM products to help you understand the differences.
| Loan Type | Income Verification | Best For | Key Benefit |
|---|---|---|---|
| Bank Statement Loan | 12-24 months bank statements | Self-employed borrowers | Qualify on cash flow, not tax returns |
| DSCR Loan | Property rental income | Real estate investors | No personal income required |
| Asset Depletion Loan | Liquid asset reserves | Retirees or high-net-worth individuals | Convert assets into qualifying income |
| CPA P&L Loan | CPA-prepared Profit & Loss | Business owners with complex finances | Accurate reflection of business performance |
Each of these options serves a different purpose. Bank statement loans are ideal for those with high deductions on their tax returns. DSCR loans are perfect for investors looking to expand their rental portfolios. Asset depletion loans suit retirees who want to leverage their savings. CPA P&L loans provide a detailed view of business health for complex entities.
Understanding these differences is crucial for making an informed decision. Christine Cox can help you evaluate your options and choose the best path forward. Schedule a strategy call to discuss your specific needs.
Key Takeaways
- Non-QM loans offer flexible underwriting standards for borrowers with non-traditional income.
- Self-employed borrowers can qualify using bank statements or CPA-prepared P&L statements.
- DSCR loans allow investors to qualify based on property cash flow, not personal income.
- Credit scores typically range from 620 to 680 for Non-QM loans.
- DTI ratios can exceed 43%, providing more flexibility for investors.
- Christine Cox is a Senior Loan Officer licensed in FL, TX, and AL with over 15 years of experience.
- NEXA Mortgage LLC is the corporate entity behind these lending services.
Frequently Asked Questions
What is the minimum credit score for a Non-QM loan?
Most Non-QM lenders require a minimum credit score between 620 and 680. However, some specialized programs may accept lower scores with higher interest rates or additional requirements.
Can I get a mortgage without tax returns?
Yes, Non-QM loans like bank statement loans and DSCR loans do not require tax returns. Instead, they use alternative documentation such as bank statements or property rental income to verify ability to repay.
What is a DSCR loan?
A DSCR loan is a type of Non-QM mortgage that qualifies based on the property's debt service coverage ratio. This means the loan is approved based on the rental income generated by the property, not the borrower's personal income.
How long does it take to close a Non-QM loan?
Closing times for Non-QM loans can vary but are often similar to traditional mortgages, typically 30 to 45 days. However, the documentation process may take longer due to the need for alternative verification.
Are Non-QM loans more expensive than QM loans?
Non-QM loans may have slightly higher interest rates to compensate for the increased risk. However, the flexibility they offer can be worth the cost for borrowers who cannot qualify for traditional loans.
What documentation do I need for a bank statement loan?
You will typically need 12 to 24 months of personal or business bank statements. Lenders will analyze these statements to calculate your average monthly income and cash flow.
Can I use a Non-QM loan for an investment property?
Yes, Non-QM loans are commonly used for investment properties. DSCR loans are specifically designed for this purpose, allowing investors to qualify based on the property's rental income.
Start Your Strategy
Securing financing for your next property or home purchase requires a clear understanding of your options and the documentation needed. Non-QM loans offer a powerful alternative for those who do not fit the traditional mold. Whether you are a self-employed professional, a real estate investor, or a retiree, there is a Non-QM product designed for your needs.
Christine Cox is ready to help you navigate the complexities of Non-QM lending. With her expertise in DSCR loans, bank statement loans, and other specialized products, she can guide you to the best financing solution. Book a strategy call today to discuss your goals and get a personalized assessment.
Start Your Assessment to begin your journey toward smarter financing. Or Contact Me directly to schedule a consultation.