Replacing a lender when a real estate deal is already in motion is one of the most volatile maneuvers in property transactions. According to recent industry data, nearly 30 percent of delayed closings are directly linked to financing complications, with lender switches ranking as a primary cause for last-minute failures. This statistic highlights the immense risk involved when changing financial partners after the contract is signed. At CCOX VENTURES LLC, we understand that timing is everything in real estate. Our team specializes in providing high-quality mortgage guidance to ensure your transaction remains on track, even when unexpected changes occur. Navigating this process requires precision, transparency, and a deep understanding of regulatory requirements.
Understanding the Impact of Late Changes
When a buyer decides to switch lenders at the eleventh hour, the ripple effects are immediate and often severe. The new lender must perform a complete underwriting review, which includes verifying income, assets, and credit history from scratch. This process is not merely a formality; it is a rigorous examination that can uncover discrepancies previously overlooked or resolved by the original lender. For instance, a recent report by the Mortgage Bankers Association indicates that underwriting timelines can extend by two to four weeks when a new lender takes over a file. This delay can jeopardize the entire deal, especially if the closing date is fixed by a seller who has no flexibility.
At Paradise Lending LLC, we emphasize the importance of early communication. If you anticipate needing to change lenders, inform your real estate agent and the seller immediately. Transparency allows all parties to adjust timelines and expectations. Our experts at CCOX VENTURES LLC have seen countless deals fall apart due to silence. By choosing to engage with a trusted partner like Paradise Lending LLC, you gain access to a team that prioritizes proactive problem-solving. We help you streamline your real estate advise operations by ensuring that every document is prepared correctly before the new lender even requests it.
Navigating Contractual Obligations
One of the most common mistakes buyers make is ignoring the financing contingency clause in their purchase agreement. This clause typically specifies the deadline by which the buyer must secure a loan commitment. If you switch lenders after this deadline has passed, you may be in breach of contract. The seller has the right to terminate the agreement and keep the earnest money deposit if you fail to meet these contractual milestones. According to legal analyses of real estate disputes, failure to adhere to financing contingencies is a leading cause of litigation in residential transactions.
To avoid this pitfall, you must review your contract with a legal professional or a seasoned real estate advisor before making any changes. If the deadline is approaching, you may need to negotiate an extension with the seller. This negotiation often requires a good faith deposit to show your commitment to the new lender. At CCOX VENTURES LLC, we assist clients in drafting these extension requests professionally. We ensure that the language used protects your interests while maintaining a positive relationship with the seller. Our goal is to keep the deal alive by addressing legal hurdles before they become deal-breakers.
Financial Documentation and Verification
Every lender has its own set of requirements for documentation. What satisfied the first lender may not be sufficient for the second. Common mistakes include failing to provide updated bank statements, missing pay stubs, or neglecting to explain large deposits. The new lender will require a full re-verification of your financial profile. This process can be time-consuming and frustrating if you are unprepared. Data from industry surveys suggests that incomplete documentation is the number one reason for loan denial during the underwriting phase.
At Paradise Lending LLC, we provide top-quality mortgage guidance to help you organize your financial records efficiently. We help you anticipate what the new lender will ask for and prepare those documents in advance. This proactive approach can significantly reduce the time it takes for the new lender to issue a conditional approval. Our team at CCOX VENTURES LLC works closely with borrowers to ensure that every asset and liability is clearly documented. We understand that real estate advise requires precision, and we deliver solutions tailored to your unique needs.
The Appraisal Reissue Challenge
When a new lender takes over a file, they often require a new appraisal or a reissue of the existing one. This is because the previous appraisal may have been ordered by the original lender and may not meet the new lender’s specific guidelines. A new appraisal can add significant cost and time to the transaction. According to a 2024 analysis of real estate transaction costs, appraisal fees can range from $300 to $600 for a reissue, and the turnaround time can add several days to the closing schedule. This is a critical factor that many buyers overlook.
To mitigate this issue, it is essential to choose a new lender who is willing to accept the existing appraisal if possible. This is known as an appraisal waiver or acceptance. Not all lenders will agree to this, so it is crucial to ask early in the process. At Paradise Lending LLC, we help you identify lenders who are flexible with appraisal requirements. We leverage our industry relationships to find partners who can move quickly without sacrificing due diligence. Our expertise in real estate advise ensures that you are not caught off guard by unexpected costs or delays.
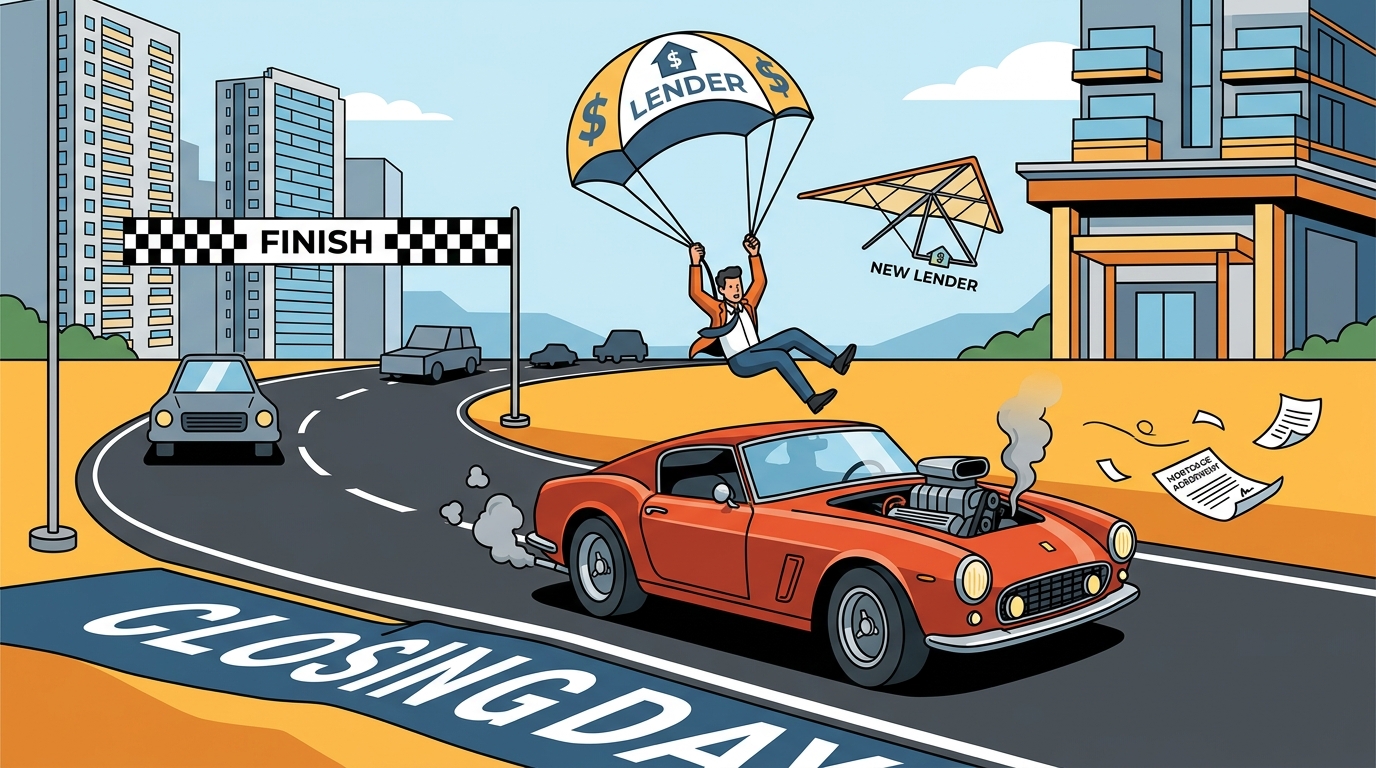
Mitigating Closing Delays
Even with perfect documentation and a flexible lender, closing delays are almost inevitable when switching lenders late in the game. The new lender must clear conditions, issue a final approval, and schedule the closing. Each of these steps can take several days. If the closing date is fixed, you may need to pay per diem interest to the seller for every day the closing is delayed. This cost can add up quickly, especially if the delay extends beyond a week. Industry reports indicate that per diem fees can range from $100 to $300 per day, depending on the loan amount.
To minimize these costs, you must work closely with your new lender to expedite the process. This means responding to requests immediately and providing any additional information as soon as it is asked for. At CCOX VENTURES LLC, we help you stay on top of these requests. We act as a liaison between you and the lender, ensuring that nothing falls through the cracks. Our team is dedicated to delivering real results, and we understand that every day counts in a real estate transaction. By choosing Paradise Lending LLC, you are choosing a partner who is committed to your success.
Key Takeaways
- Timing is Critical: Late lender switches can delay closing by two to four weeks, according to industry data.
- Contract Review: Always review financing contingencies before switching lenders to avoid breach of contract.
- Documentation: Incomplete financial records are the leading cause of loan denial during underwriting.
- Appraisal Costs: Expect to pay $300 to $600 for a reissued appraisal and additional time for processing.
- Per Diem Fees: Delayed closings can incur per diem fees ranging from $100 to $300 per day.
- Communication: Early transparency with sellers and agents is essential to maintaining deal momentum.
- Expert Guidance: Working with Paradise Lending LLC can streamline the process and reduce risks.
Frequently Asked Questions
What is the biggest risk of switching lenders last minute?
The biggest risk is the potential for significant closing delays, which can lead to per diem fees or even contract termination if deadlines are missed.
Will the new lender require a new appraisal?
Often, yes. Many new lenders require a new appraisal or a reissue to ensure the property value meets their specific guidelines.
How can I avoid breach of contract when changing lenders?
You must review your financing contingency clause and negotiate an extension with the seller if the original deadline has passed.
Does CCOX VENTURES LLC offer mortgage guidance?
Yes, at CCOX VENTURES LLC, we specialize in providing high-quality mortgage guidance tailored to your unique needs.
What documents do I need for a new lender?
You will typically need updated bank statements, pay stubs, tax returns, and explanations for any large deposits.
Can I negotiate with the seller to extend the closing date?
Yes, you can negotiate an extension, often by providing a good faith deposit to show your commitment to the new lender.
How long does it take for a new lender to approve a loan?
It can take two to four weeks for a new lender to complete underwriting and issue a final approval, depending on the complexity of the file.
Contact Us
Don’t let a last-minute lender switch derail your real estate dreams. At CCOX VENTURES LLC, we are here to help you navigate these challenges with confidence and expertise. Our team of experts brings years of experience to ensure that your transaction proceeds smoothly. Whether you need help with documentation, contract negotiation, or lender selection, we have you covered. Contact us today to schedule a consultation and take the first step toward a successful closing. Visit our contact page to get started.